In this article
Automatic categories sound like the answer to an annoying rewards chore. You spend normally, and the card works out where to give you the higher rate.
That is a useful convenience. It does not guarantee a higher total reward. When a large part of the household budget earns 1%, the convenience can coexist with a weaker result than a simple 2% card.
The interesting opportunity is more specific: use Venmo for an eligible category that deserves the 3% rate, especially where other cards have narrower merchant definitions. Then decide whether it needs to handle anything else.
Our take: automatic selection works best with a clear spending pattern
Our recommendation: Consider Venmo Credit Card when one eligible category reliably leads your spending and the app-based cash-reward routine suits you. Compare the entire statement period with a flat-rate card, particularly if many purchases fall into Other. Current Venmo card
- Good fit if: You prefer automatic category ranking and have a substantial, qualifying grocery, warehouse, bill or other leading category.
- Consider another card if: Purchases are spread broadly, Other is large or you want a predictable higher rate in several categories at once.
- The tradeoff: In our model, using Venmo for $6,000 of qualifying groceries and warehouse purchases beside a 2% fallback adds $60 a year, or $5 a month. Using Venmo for the entire budget earns less than 2%.
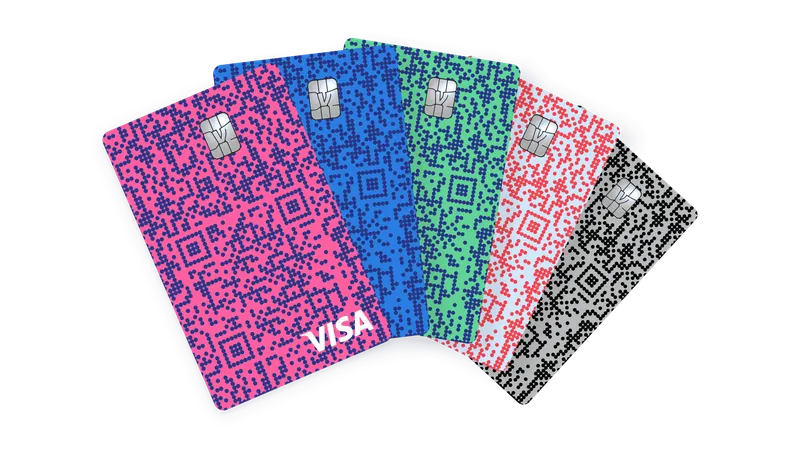
This review covers the Synchrony-issued Venmo Visa Credit Card, including Visa Signature where issued. It is different from the Venmo debit card and from funding a Venmo payment with another credit card.
Venmo Credit Card rewards and fees at a glance
| Feature | Reviewed terms |
|---|---|
| Annual fee | $0 |
| Top eligible category each statement period | 3% |
| Second eligible category | 2% |
| Other eligible purchases | 1% |
| Ordinary higher-rate purchase cap | None in the reviewed 3%/2% rules |
| Purchase APR when opened | 18.74%, 27.74% or 30.74%, depending on account type; variable thereafter |
| Foreign transaction fee | None |
| Paper-statement charge | $1.99 in a cycle meeting the stated conditions |
| Public welcome bonus in our model | $0; no unverified personalized promotion included |
Paper statements incur that fee when the balance exceeds $2.50 and a monthly paper statement is sent. Electronic-only delivery avoids the charge under the reviewed terms. Cash advances carry a 30.74% variable APR and a 5% fee with a $10 minimum. Late and returned payments can each cost up to $41, and a 34.24% variable penalty APR may apply under the agreement's conditions. No general introductory purchase APR is assumed here. Pricing agreement
Applications run through the Venmo app. The public requirements include being at least 18, living in the U.S. or its territories, and having a Venmo account open at least 30 days and in good standing. An approved application results in a hard credit inquiry. The pricing disclosure expects only a limited number of applicants to receive the lowest-rate account type; app access or a familiar Venmo balance does not establish approval or that rate. Application requirements Rate qualification
Eight categories compete for the higher rates
The eligible categories are Dining & Nightlife, Travel, Bills & Utilities, Health & Beauty, Grocery, Gas, Transportation and Entertainment. Ranking takes place each statement period. Other cannot receive 3% or 2%, even if it contains the most spending. Category and ranking rules
That last rule is the one we would underline. “Your top category” sounds broader than it is. A $1,500 expense placed in Other does not become a 3% purchase just because it dominates the statement.
Venmo's public category examples include wholesale clubs in Grocery and phone, internet and streaming in Bills & Utilities. Those groupings can make the card useful where a narrower supermarket or utility definition would not fit. The actual merchant code and transmitted transaction information still control. If a third-party payment service or digital wallet does not pass along the merchant code, the purchase earns 1%. That is a transmission condition, not a blanket exclusion of every mobile-wallet purchase. Category examples Merchant-code rules
Do not assume everything in a personal budget category receives the same treatment from the issuer. Your budget may call a restaurant meal “entertainment” and a warehouse shopping trip “household.” The reward calculation follows the card's classification.
The store-category guide explains how that distinction affects Walmart, Target, Costco and other mixed-product retailers. For a card you already hold, a posted transaction is more useful evidence than a guess based on the store's name.
What an ordinary household earns
Our $24,000 annual model spreads spending evenly across twelve statement periods. Qualifying groceries, including the warehouse budget, total $500 each cycle. Dining is $300. Bills and utilities total $280; other eligible ranked categories are smaller.
Groceries therefore take 3%, dining takes 2% and the remaining spending earns 1%.
| Annual purchase group | Spending | Rate in this model | Reward |
|---|---|---|---|
| Qualifying Grocery, including warehouse purchases | $6,000 | 3% | $180 |
| Dining & Nightlife | $3,600 | 2% | $72 |
| All remaining eligible purchases | $14,400 | 1% | $144 |
| Total | $24,000 | – | $396 |
A suitable 2% card produces $480, which is $84 more. The automatic ranking saves a selection task, but it cannot make up for earning only 1% on $14,400 of the budget.
The first-year model is also $396 because we have not added a personalized promotion that every reader may not receive. If the app presents an offer, evaluate its actual eligibility, spending and time requirements separately.
All examples use planned eligible purchases, no returns or extra payment fees, usable cash rewards and full on-time payments preserving the purchase grace period. They are modeled scenarios rather than reports of our own card use. Statement boundaries and merchant treatment can change an actual result.
A focused grocery role can work better
Suppose the same household puts only its $6,000 in qualifying groceries and warehouse purchases on Venmo, with no competing higher eligible category. Those purchases earn $180 at 3%. Put the remaining $18,000 on a suitable 2% fallback for $360.
The pair earns $540. That is $60 more than a 2% card alone and $144 more than using Venmo for the whole budget.
The $60 figure is the relevant improvement when deciding whether to add Venmo to an existing 2% wallet. It pays you $5 a month for keeping a simple rule. The larger $144 figure also includes fixing the 1% fallback on other purchases.
This role can be particularly interesting for qualifying warehouse shopping, because many supermarket bonuses exclude warehouse clubs. But check that the card is accepted through the shopping channel you use and that the purchases actually receive Grocery treatment.
You do not need to put a second category on Venmo merely because it offers a second-place rate. If your fallback already earns 2%, moving another category to Venmo at 2% adds no reward by itself. It can also change which group ranks first during an unusual statement period.
The one-card or two-card guide compares this focused approach with other straightforward pairings.
Statement periods matter more than annual averages
A year-end spending summary can hide the way categories trade places. Venmo recalculates each statement period, so a travel-heavy month can have a different winner from an ordinary grocery month.
Consider two cycles:
| Purchase category | Cycle one spending | Cycle one reward | Cycle two spending | Cycle two reward |
|---|---|---|---|---|
| Grocery | $500 | $15 at 3% | $100 | $1 at 1% |
| Dining | $300 | $6 at 2% | $300 | $6 at 2% |
| Gas | $100 | $1 at 1% | $500 | $15 at 3% |
| Total | $900 | $22 | $900 | $22 |
The actual two-cycle total is $44. Combining all spending first would show a three-way $600 tie. Applying 3%, 2% and 1% to that pooled total would incorrectly produce $36, understating these two cycles by $8. The account does not retroactively rank the whole year as one statement.
For equal eligible category totals, the agreement's listed category order determines which receives the higher rate. A tie does not award 3% to both groups. Tie and statement-period rules
Here is another ordinary-life example. A cycle with $500 groceries and $300 dining earns $21: $15 plus $6. Add a planned $1,000 qualifying travel purchase. Travel now earns $30 at 3%, groceries earn $10 at 2%, and dining earns $3 at 1%, for $43 total.
The travel purchase increased rewards by $22, not the full $30, because the earlier categories moved down. If that same $1,000 travel purchase went to a 2% fallback while the original $21 stayed on Venmo, the combined reward would be $41. The difference between those two routing choices is $2.
That is useful perspective before spending time trying to micromanage category rankings.
A large Other category stays at 1%
Suppose a statement contains $1,000 in Other, $400 in qualifying groceries and $200 in dining. The result is $10 plus $12 plus $4, or $26. A 2% card earns $32 on the same $1,600.
If Other mistakenly received 3%, the estimate would be much too high. This is why a review calling Venmo “3% on whatever you spend most on” would be misleading.
For a simple comparison, let the top eligible category's spending be A and second-place spending be B. Let C include all purchases earning 1%, including Other. Venmo earns 3% of A, 2% of B and 1% of C. Compared with a flat 2%, the advantage is one percent of A minus one percent of C.
In plain language, the top eligible category must be larger than all the 1% spending combined for this simplified one-card setup to beat 2%. The second-place category is a tie with the fallback.
On our annual model, A is $6,000 and C is $14,400. One percent of their $8,400 difference explains Venmo's $84 shortfall. This works because the same categories hold their positions in each modeled cycle; changing rankings require the cycle-by-cycle calculation above.
Automatic cash rewards still need a payment routine
Calculated rewards move automatically into the linked Venmo balance after the statement period, generally within three business days and no later than one statement period under the agreement. The card and Venmo accounts must remain open, linked and in good standing. Reward transfer rules
This can feel convenient if you already use Venmo. It can also make the reward easy to spend without noticing. Decide whether you want it to offset an ordinary expense or move to a linked bank account, and check any transfer fee or delay.
Cash in the Venmo balance is separate from the credit-card payment. Confirm the amount due and payment status rather than assuming that the app has applied a reward toward the statement automatically.
The app's running reward display is an estimate until the period's calculation finishes. Later purchases, returns and transaction adjustments can change it. Review the completed statement before using the estimate to judge whether a category strategy worked.
Closure rules also differ depending on what closes and who initiates it. A voluntary card closure generally transfers pending earned rewards at period end under the agreement; closure by Synchrony, unlinking or closing the Venmo account can cause forfeiture, subject to applicable exceptions. Check the actual sequence before making account changes. Account-status rules
No foreign fee is useful; paper statements have a cost
The reviewed pricing charges no foreign transaction fee. That gives Venmo a potential advantage over a similar card charging 3% abroad, provided the purchase earns the expected reward and the merchant accepts the card.
For example, a $1,000 eligible foreign purchase at a 1% reward returns $10 with no issuer foreign fee. A hypothetical 2% card charging a 3% foreign fee returns $20 but charges $30, leaving a $10 shortfall. Venmo comes out $20 ahead in that narrow fee comparison.
It still deserves comparison with suitable cards offering both a higher ordinary rate and no foreign fee. The absence of one charge does not settle the entire card choice.
Paper statements create a smaller recurring cost. Twelve qualifying $1.99 charges total $23.88. That reduces the $60 annual gain from the focused grocery pairing to $36.12 before other costs. If you prefer paper, include it; if electronic delivery works for you, the reviewed terms provide a way to avoid that specific fee. Fees and delivery conditions
Personal payments do not become a bonus category
The reward agreement assigns qualifying purchase-classified personal transfers a 1% rate. Cash advances do not qualify. That is a separate payment-treatment rule, and fees can exceed any reward. Personal-transfer terms
Our shopping examples exclude personal transfers. Splitting a dinner with friends does not create another restaurant purchase when a reimbursement arrives. The card's QR code can help with that social payment process, but it does not multiply the underlying meal's reward.
For payment mechanics, use the existing send-money guide. For costs, compare the available routes in the payment-fee guide.
Alternatives you can compare quickly
| If you want… | Compare… | The key distinction |
|---|---|---|
| Stable rewards in several qualifying food categories | Capital One Savor | Its grocery, dining and other eligible categories do not compete for first place, but merchant definitions differ |
| A higher rate based on checkout rather than category | PayPal Cashback Mastercard | Qualifying PayPal use earns 3%, with a 1.5% fallback and different fees |
| A specialist for selected household bills | U.S. Bank Cash+ | Higher selected-category rates require activation and have a shared quarterly cap |
| A single ordinary rate | PNC Cash Unlimited | Broad 2% rewards without category ranking or a foreign transaction fee |
The PayPal-versus-Venmo comparison helps identify whether checkout share or category concentration better matches your purchases.
For Venmo, we would first look for a reliable leading category. If it exists, the card can have a useful, fairly simple job. If it does not, automatic ranking may be convenient without being the strongest reward arrangement.
Frequently asked questions
Can Other be the 3% category?
No. Other always earns 1% under the current rules, even if it contains more spending than any eligible ranked category.
Are categories selected once a year?
No. They are ranked for each statement period. Annual totals can hide changes between cycles and lead to an inaccurate estimate.
Can qualifying warehouse purchases count as Grocery?
Yes. The reviewed Grocery definition includes wholesale clubs. Merchant classification, transmitted purchase information and card acceptance still matter for the particular transaction.
Do I need to request the cash reward every month?
The calculated reward transfers automatically to the linked Venmo balance under the program's timing and account-status conditions. Moving it onward to a bank is a separate choice.
Does a personal transfer earn 3% if it is my largest expense?
No. Qualifying purchase-classified personal transfers receive 1%, and cash advances do not earn rewards. Separate fees and transaction rules still apply.
How we evaluated this card
We reviewed the issuer terms and sources linked below and compared modeled, planned household purchases at documented cash-redemption values. Examples distinguish introductory offers from ongoing value and show relevant caps, exclusions and costs. They are illustrations, not personal card-use claims or approval predictions.
Product, pricing and rewards terms checked September 15, 2026.
Sources & references3 sources
The issuer terms and other references behind this article.